Historical-source note: Biteye published the original analysis on November 11, 2026, at 11:03 a.m. UTC+8. Figures below retain the source’s reporting dates; they are not current measurements.
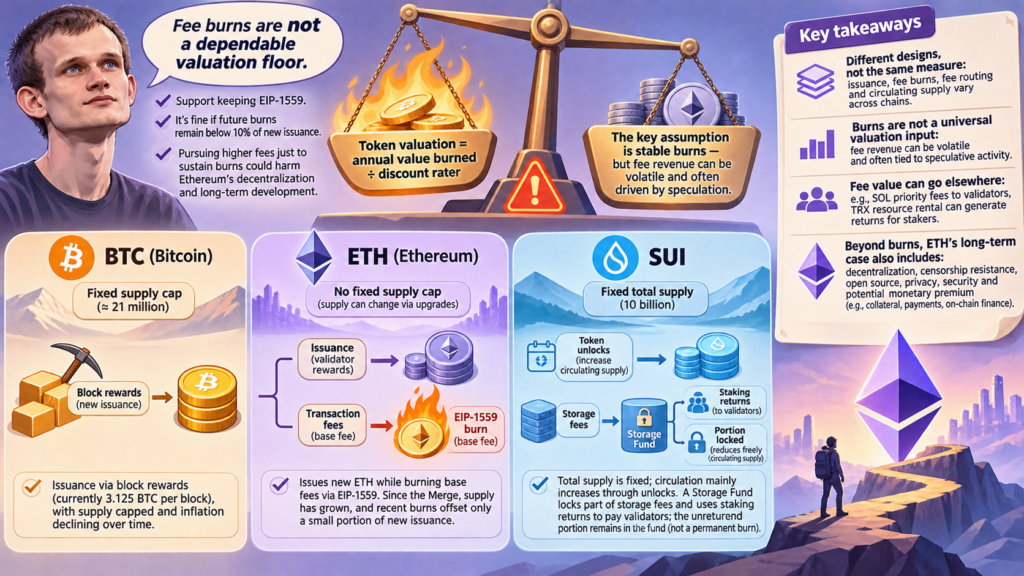
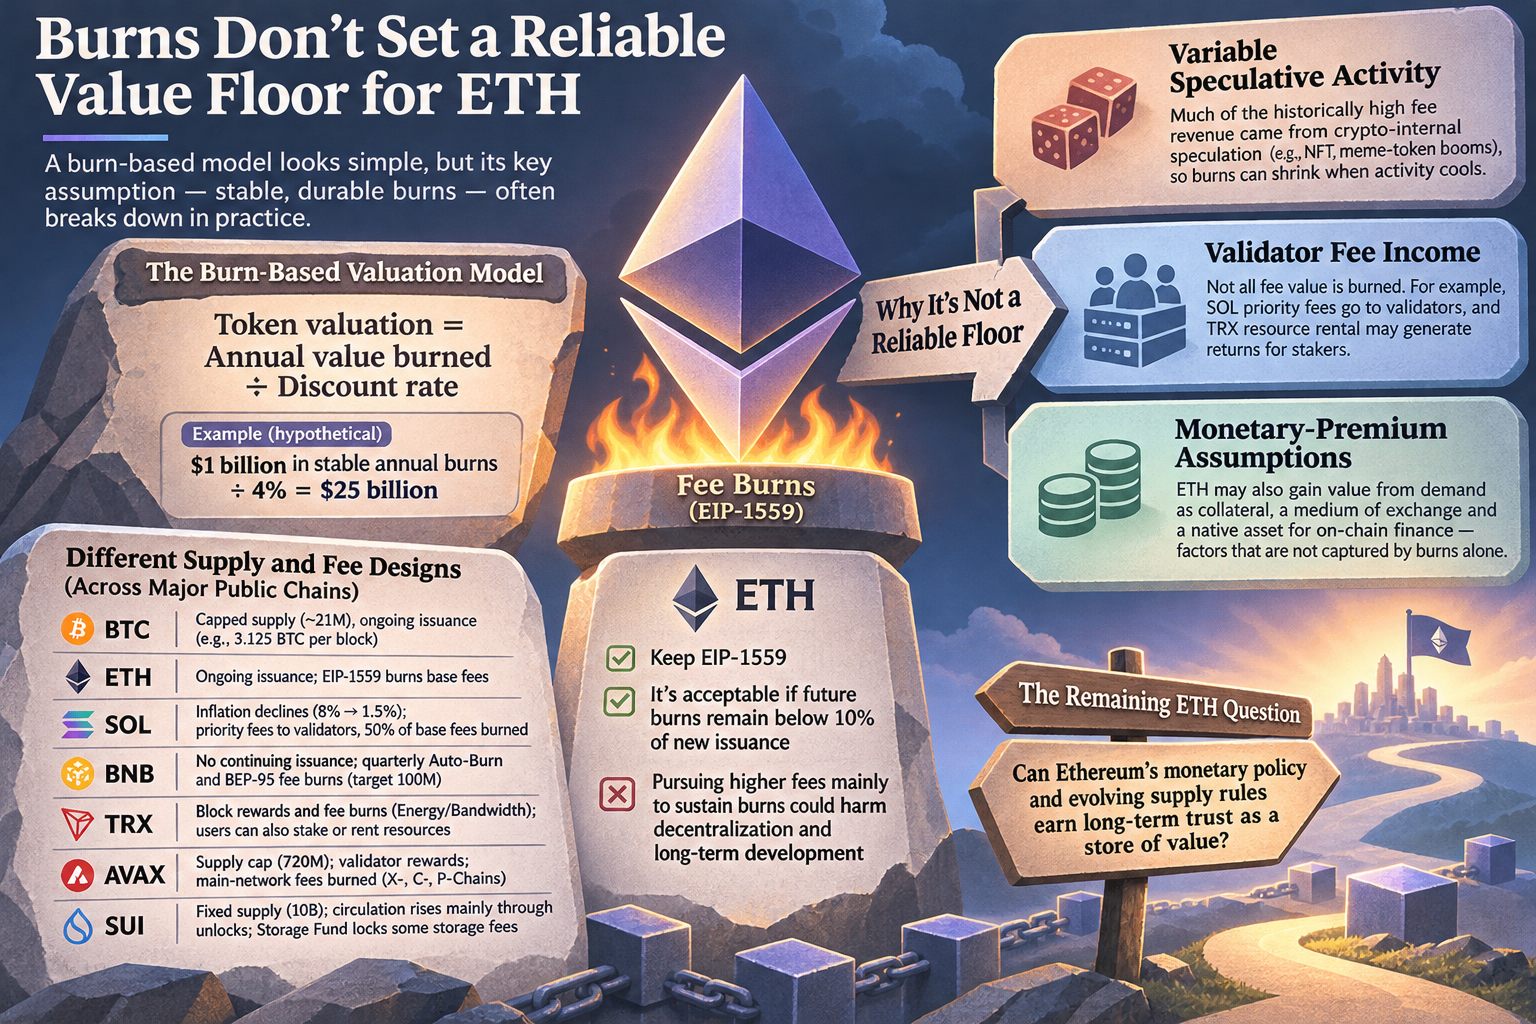
A November 8 post by Vitalik Buterin challenged a familiar way of valuing ETH: if network use produces fees and fees are burned, can that burn provide a dependable floor for the token’s value? As Biteye reported, Buterin argued that it cannot. Much of the historically high fee revenue came from speculation within crypto, so burns could shrink when that activity subsided. He still supported retaining EIP-1559, but said it would not be a problem if future burns remained below 10% of new issuance. Pursuing higher fees chiefly to sustain burns could, in his view, harm Ethereum’s decentralization and long-term development.
Supply change is not one mechanism
Biteye’s comparison shows why issuance, fee burns and circulating supply need to be examined separately:
- BTC: Supply is capped at approximately 21 million. At a 3.125 BTC block reward and an assumed average of one block every ten minutes, the source estimated annual issuance at roughly 164,300 BTC, or 0.82% annualized supply inflation.
- ETH: Biteye reported approximately 1.37% cumulative supply growth since the 2022 Merge. EIP-1559 burns base fees, but the source said burns over its most recent 30-day measurement period offset only about 3.2% of new issuance, amid L2 adoption and lower gas fees.
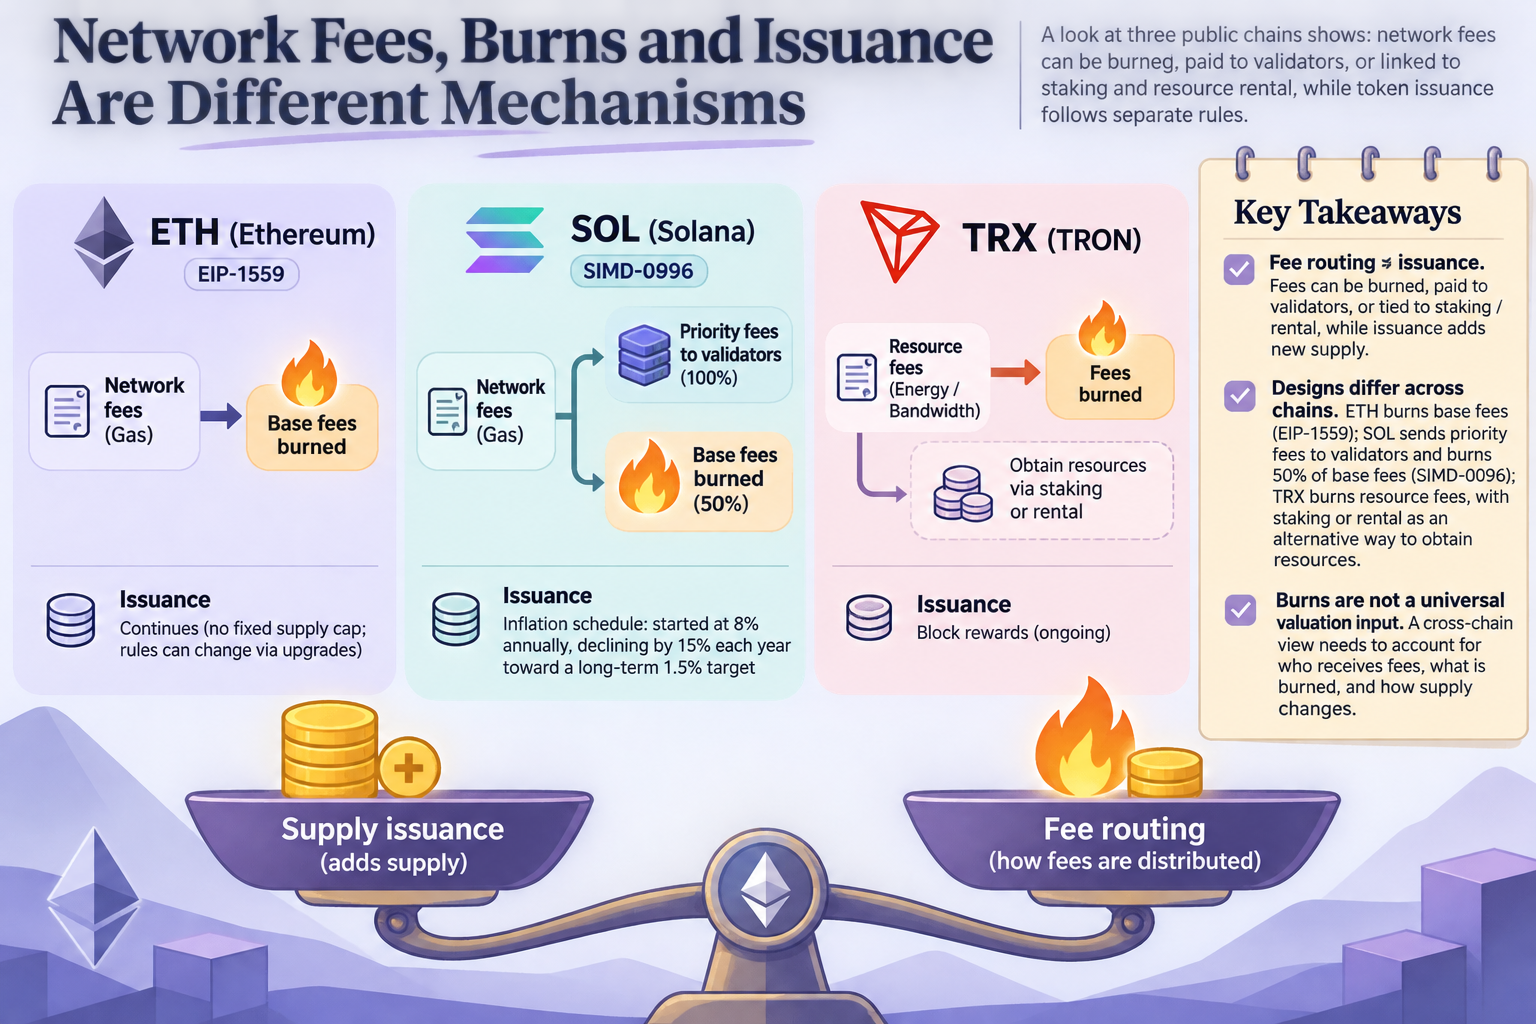
- SOL: Solana’s stated inflation schedule began at 8% annually, declining by 15% each year toward a long-term 1.5% target. During the 2024 meme-token boom, daily burns at one point exceeded 10,000 SOL; in January 2025, burns offset about 23% of issuance. Following implementation of SIMD-0096, priority fees went entirely to validators while 50% of base fees were burned. Biteye said daily burns subsequently fell at one point to about 700 SOL.
- BNB: Rather than relying on continuing issuance, BNB reduces supply through quarterly Auto-Burn and BEP-95 fee burns, toward a target of 100 million tokens. Biteye reported approximately 6.2 million BNB burned across the first four quarterly burns of 2026. Auto-Burn depends on token price and block production; BEP-95 burns part of network fees.
- TRX: TRON issues block rewards and burns fees paid for Energy and Bandwidth. Users can also obtain those resources by staking or renting them, so more USDT transfers do not necessarily mean proportionately more TRX burned.
- AVAX: AVAX has a 720 million token supply cap and issues validator rewards; fees on its main-network X-, C- and P-Chains are burned. As of early November 2026, Biteye reported roughly 474 million AVAX minted, including about 114 million in staking rewards, against approximately 5.18 million burned. Burns had not offset issuance.
- SUI: Its total supply is fixed at 10 billion, while circulation rises principally through unlocks. Its Storage Fund locks some storage fees and uses staking returns to compensate validators. Deleting data can return most of a fee; the unreturned portion remains in the fund, reducing freely circulating supply rather than being permanently burned.
These are different supply and fee-routing designs, not directly interchangeable measures of tokenholder value.
Where a burn-based valuation breaks down
Biteye examined a simplified model discussed by Buterin: token valuation = annual value burned ÷ discount rate. A hypothetical $1 billion in stable annual burns at a 4% discount rate yields $25 billion. The critical assumption is stable: the equation treats future burns much like a durable cash flow.
The source reported that Ethereum burned about 1.48 million ETH, worth approximately $3.6 billion, in 2022. From the start of 2026 through November 8, it reported only about 19,200 ETH burned, worth approximately $43 million. Biteye’s illustrative annualization of that latter amount was roughly $50 million. Applying the same 4% rate produces a valuation of about $1.25 billion, versus an ETH market capitalization of approximately $270 billion at the time—a gap exceeding 200-fold. That comparison exposes the model’s limits; it does not establish an alternative fair value.
Burns also omit value routed elsewhere. Under the fee arrangements described above, SOL priority fees go to validators, while TRX resource rental may generate returns for stakers. Conversely, high burns driven by episodic speculation are not evidence of a persistent revenue stream. A cross-chain analysis must account for who receives fees, what is burned and how supply changes, rather than treating the burn total as a universal valuation input.
The remaining ETH question
According to Biteye, Buterin placed greater weight on Ethereum’s decentralization, censorship resistance, open-source character, privacy and security, particularly as AI advances. The source also raised competing considerations: demand for ETH as collateral, a medium of exchange and a native asset for on-chain finance might contribute to a monetary premium that fee burns alone cannot explain. Yet ETH has no fixed supply cap, and protocol upgrades can change issuance rules. Whether its monetary policy can earn the long-term trust associated with a store of value remains an open question—not something the reported burn figures can settle.
Source: panewslab.com (originally published 2026-11-11 11:03 UTC+8)