In a report published on November 18, 2026, Bitcoin’s decline raised a question that cost-basis and on-chain measures could not yet settle: was the June low likely to hold? The report said Bitcoin had fallen from about $74,000 to a November 15 low near $61,900 in five days. It put 24-hour liquidations near $2 billion, more than 80% of them long positions, and the fear index at 10. These were reported readings, not evidence that a bottom had formed.
What the cost bases show
The report placed Bitcoin near $65,000 when discussing several cost estimates above the market price: an ETF average holding cost of about $81,500, attributed to Glassnode data dated October 27; a market-wide average near $77,500; a short-term-holder cost basis near $75,600; and Strategy’s average purchase price near $75,400. It did not name datasets or measurement dates for the latter three estimates. At the reported price, Strategy’s holdings would have been roughly 14% below that average purchase price.
Below the market, the report identified June’s low as a range of roughly $57,700–$58,500 and a network-wide average holding cost around $53,000–$55,000. A cost basis describes where coins were acquired; it does not establish a price floor.
The report also cited Glassnode data indicating that about four million BTC had been acquired between $85,000 and $118,000. It said the share of supply in profit had fallen from 60.4% to 55.3%, its lowest since August, while short-term holders were collectively at an unrealized loss of 7.4%, with only about one-third still in profit. Those measures indicate pressure on holders, but cannot establish when—or whether—they will sell.
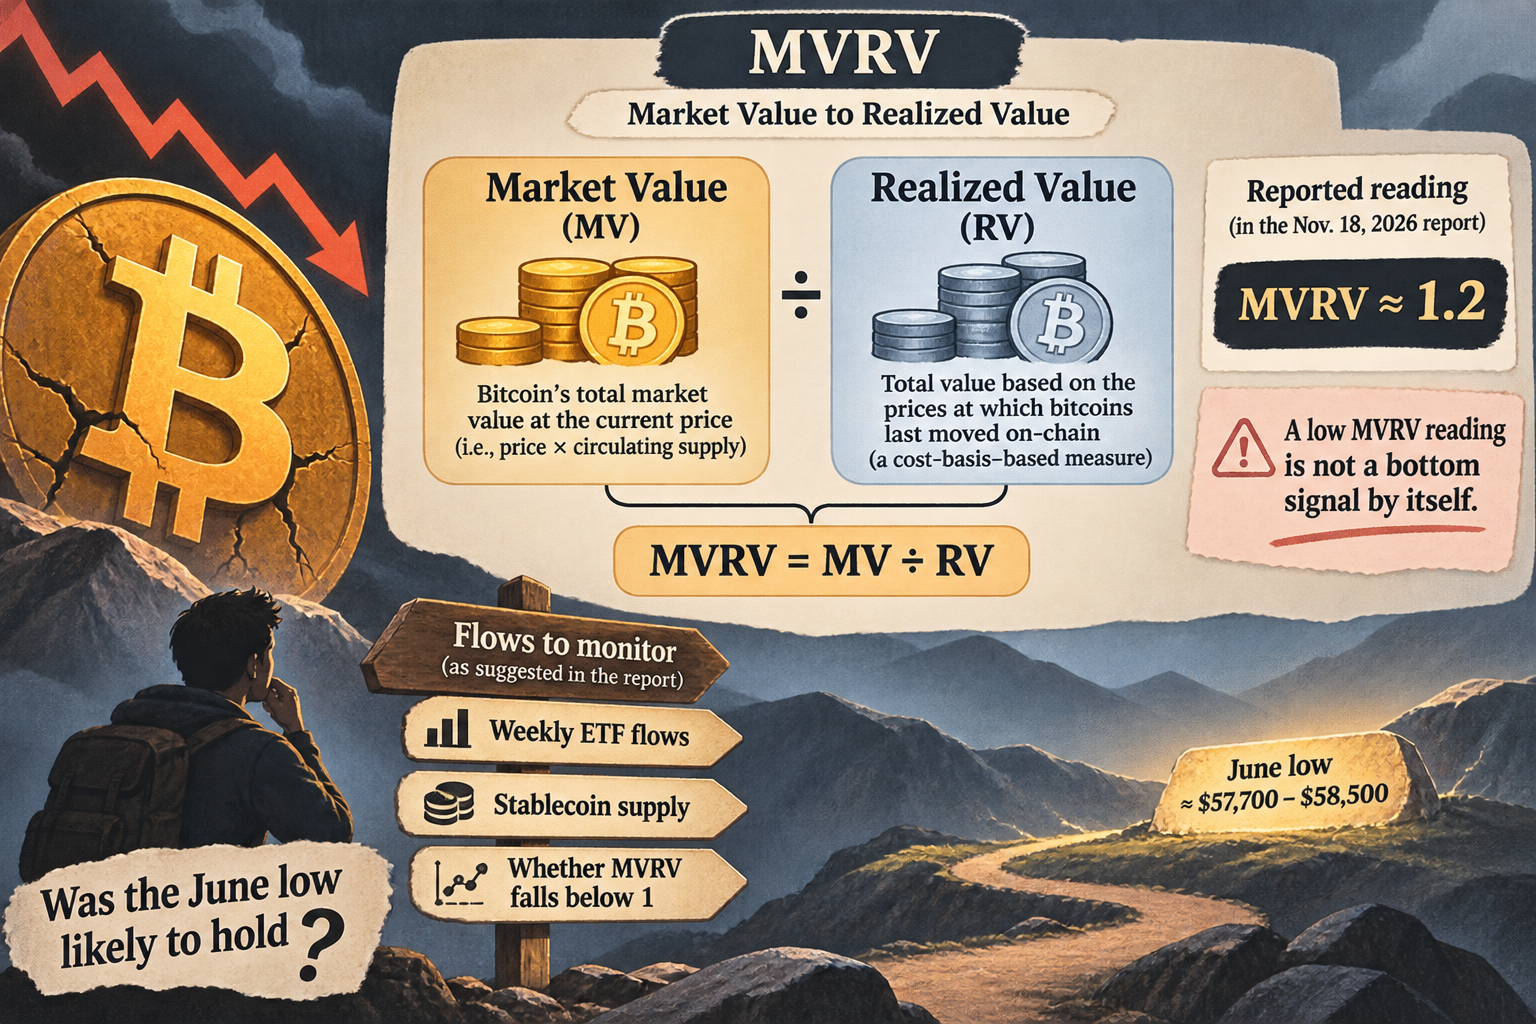
A low MVRV reading is not a bottom signal by itself
MVRV compares market value with realized value, a measure based on the prices at which coins last moved on-chain. The report put MVRV near 1.2. CryptoQuant analyst Darkfost called it the third low-level signal from his model in 2026, after signals in February and June–July, while cautioning that three signals in a bear market do not imply three bottoms.
The report contrasted that reading with criteria set out by Galaxy research head Alex Thorn in June: past bottoms typically occurred 12–13 months after a peak, with MVRV below 1 and price below realized price. By November, the report said, 13 months had elapsed, but MVRV had reached only 1.14 at its lowest and price remained about 20% above realized price. Thorn also noted that this cycle’s peak MVRV, at 2.29, was lower than in earlier cycles—an argument against assuming that any eventual bottom must match their depth. The report cited Galaxy scenarios spanning $51,000 to $30,000, with a $40,000–$46,000 base case. These are scenarios, not measured support levels.
Historical comparisons are similarly inconclusive. The report noted that Bitcoin fell from roughly $17,600 in June 2022 to $15,500 after FTX’s collapse five months later; in 2018, it fell from a prolonged period around $6,000 to about $3,122. Neither sequence establishes that the June 2026 low must be broken.
Flows to monitor
According to the report, spot Bitcoin ETFs recorded more than $2.3 billion in cumulative net outflows from late October through November 13, with net inflows on only two of 12 trading days. It also reported a roughly $14.2 billion contraction in stablecoin supply over 30 days. In the other direction, it said wallets holding 100–10,000 BTC continued accumulating and cited Glassnode’s assessment that cumulative ETF outflows remained relatively shallow against the funds’ total size.
The report proposed watching weekly ETF flows, stablecoin supply and whether MVRV falls below 1. Those indicators could clarify the balance of demand and holder stress. None, alone, can determine whether the reported June low was Bitcoin’s cycle bottom.